

Early adoption of FX algos focused on basic access. For example can the provider offer TWAP, VWAP and liquidity-seeking strategies? The question has shifted to can the provider show that these algos improve outcomes? How have providers responded to that?
At NatWest Markets, we are placing a strong emphasis on demonstrating measurable improvements in execution outcomes. To support this, we have invested heavily in performance measurement frameworks, combining internally developed MIS capabilities with external analytics providers such as TradeFeedr.
These frameworks support multiple important use-cases. Primarily, they enable the ongoing evaluation of Algorithmic performance, particularly through metrics such as slippage versus the inception-mid benchmark, and feed directly into the ongoing optimisation of our Algorithmic execution logic. Robust measurement frameworks additionally facilitate controlled A/B-testing, allowing us to compare different configurations and validate the impact of new features before they are deployed. This is something we feel strongly about at NatWest Markets. Enhancements to client Algorithms are systematically tested, leveraging internal trading desk flow, to ensure they deliver tangible benefits. It is worth noting that the biggest users of our Algos are our internal trading desks, who trust the same Algos our clients rely on. Importantly, performance measurement capabilities are also used to enhance transparency for our customers. We can clearly demonstrate how recent improvements have translated into better execution outcomes, whilst integrating with third-party analytics providers allows clients to compare performance across multiple providers.
Before a trade is executed, portfolio managers and traders want clarity on the expected cost and risk. In what ways is pre-trade analytics becoming essential in helping buyside desks ascertain how a trade should be executed before committing to an algo?
While absolute clarity on expected costs and risk is impossible to provide, pre-trade analytics have become increasingly important in providing informed guidance on execution strategy. Leveraging a large dataset of Algo runs from customers and internal trading desks, we can offer various measures of execution costs. These include slippage to key benchmarks, their variability and typical execution speeds.
Real-time measures of liquidity are important too. The consideration between using an Algo order or trading via risk-transfer should take into account a real-time assessment of liquidity conditions. For instance, during periods of non-standard liquidity observed in March this year, we observed elevated volatility levels and increased trading volumes. Wider bid-offer risk-transfer spreads and a higher likelihood of passive fills made Algorithmic execution more attractive. We noticed a meaningful shift in execution behaviour with a notable increase in both the relative and absolute use of Algos.
Transaction Cost Analysis has now moved from “nice to have” to a regulatory and fiduciary requirement. What type of information do buyside firms want TCA to deliver?
TCA has evolved from a reporting tool into a core component of delivering best execution. Whilst post-trade TCA remains the most important for demonstrating best execution, buyside firms are increasingly looking for a more holistic view that spans the whole trade lifecycle. Pre-trade and real-time analytics play a key role in helping firms actually achieve best outcomes, not just measure them after the fact.
A survey on TCA services and Algorithmic trading we conducted last year with a global group of customers across various segments yielded some interesting results:
- “Liquidity” was the #1 factor considered for pre-trade and real-time TCA, but typically no longer assessed as part of post-trade analyses
- “Expected Costs” and “Expected Trade Duration” are the #2 and #3 most-used factors for pre-trade TCA, but are least used for real-time TCA Instead, “Running performance vs benchmarks” and “Fill-type breakdowns” become important
- For post-trade TCA services, “Performance vs benchmarks” stands out, followed by “Breakdown of liquidity sources used”
This demonstrates that the type of information buyside firms want TCA to deliver is very dependent on the moment it is accessed during a trade’s lifecycle.
Execution is no longer a standalone activity. It must integrate seamlessly with the broader trading workflow. In what ways have providers worked to deliver FX algo trading toolsets that can meet key integration demands and also reduce manual intervention and operational risk across the trading lifecycle?
We are observing a growing interest from buyside clients for more integrated and configurable execution solutions, with Direct API connectivity playing a central role. Key reasons cited for this demand are to support bespoke tailor-made trading workflows and reduce brokerage costs.
From an execution perspective, Direct API connections allow for more flexible configurations. For example, customers can directly connect to our proprietary liquidity venue COMS (Client Order Matching System), enabling them to manage passive order placement themselves, rather than delegating this to an Algo.
Beyond execution, a Direct API integration can facilitate and simplify the full trading lifecycle. Post-trade processes such as netting and allocation can be fully automated and tailored to individual user requirements, while risk controls, such as fat-finger limits, can be configured to align with firm-specific risk management frameworks.
The buyside is moving away from one-size-fits-all algos with customisation and control becoming increasingly important. How are providers meeting these expectations and in what ways is algo execution becoming more personalised to each firm’s trading style?
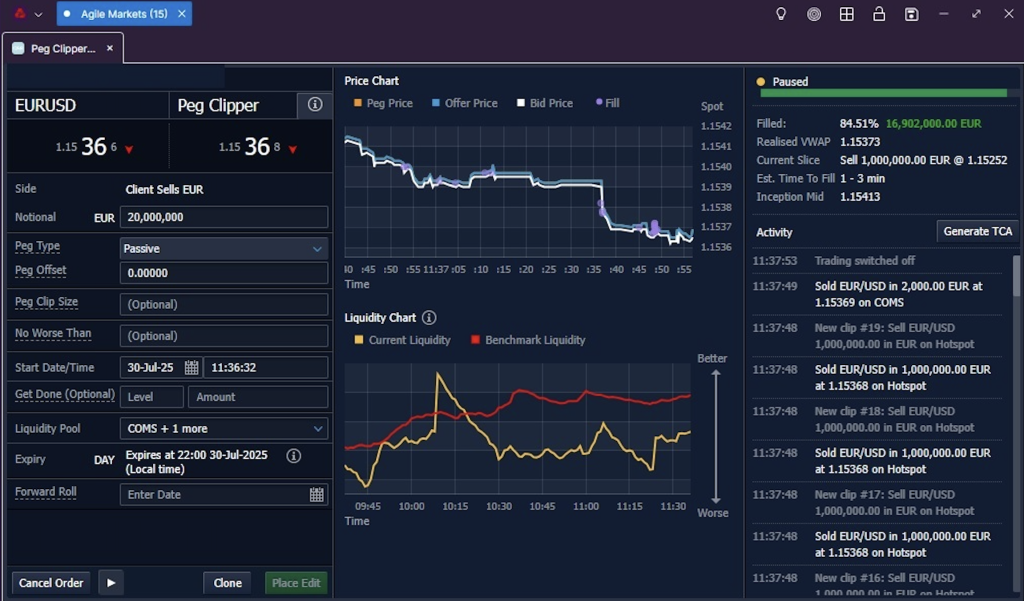
Offering extensive customisability is key to cater to a broad client-base with varying trading requirements. Various parameters can be set by clients directly on order tickets or via FIX, including the configuration of liquidity venues to be accessed for passive placement. Some advanced routing rules can be set on the customer’s behalf as well, such as liquidity access configurations at a more granular level. At NatWest Markets, we additionally support configurable default settings across all Algorithm parameters, minimising the need for manual inputs at time of execution, saving time and reducing human error.
Many buyside firms increasingly view execution providers not as vendors, but as strategic partners expected to deliver algos and also execution intelligence. What does that look like in practice?
We absolutely see ourselves as strategic partners to our clients, collaborating closely to understand our client’s objectives so we can help them deliver them. Buyside firms and bank trading desks fundamentally share the same goal when managing risk: clearing a position as cheaply as possible, minimising market impact. Given this, buyside firms greatly appreciate access to the execution methods and TCA services that banks have developed, and value discussions with bank trading desks on how best to utilise these solutions.
An example is our proprietary liquidity venue COMS (Client Order Matching System), which is a core component of our Algos. It allows client order interest to be matched with suitable counterparties across our broader franchise who respond appropriately to skewed interest. By accessing COMS through our Algos, clients benefit directly from years of experience developing and refining skew leakage monitoring frameworks.
What are some of the major differentiators between FX algo providers and how important have trust and explainability become in that evaluation?
Through the emergence of third-party TCA providers, Algo performance has become increasingly measurable and comparable. Besides allowing sufficient customisability to support a range of execution requirements across a client-base, a way to differentiate yourself as provider is ultimately for your Algos to show strong performance.
The next “nth generation AI-powered” Algorithmic order-type will simply be judged by its performance versus inception mid, rather than its perceived complexity. Explainability is fundamental to having confidence in consistency of behaviour. We do not use AI but purposely employ “rules based” execution logic to ensure we are always able to explain why our Algos did what they did.
Liquidity is one of the most important determinants of an Algo’s performance and we take liquidity curation incredibly seriously. We are constantly measuring market impact of order placement and our distributed ticks. Minimising market impact is a key driver of the ongoing success of our flagship passive Algo, “Peg Clipper”. It’s fair to say that liquidity curation isn’t just important to us, we take pride in our approach and see it as a USP.
